How to purchase real-estate in Japan as a foreigner
*English version of the Korean post I have uploaded in 2024
Before we start
I've been getting the same questions from friends who are thinking about buying property here. So I wrote down what I learned while going through it myself.
Why buy
Over a 10–15 year horizon, I expect central Tokyo prices to keep climbing.
We're planning to have kids, and our current place was small. We were already looking at moving anyway.
What we were looking for
At first I had no feel for any of it. But after a week of poking at listing sites whenever I had a spare moment, a sense of the market starts to form. I began with loose filters to see as wide a range as possible, then tightened them as I went. After viewing a few places in person, it also became clear which conditions we could compromise on and which we couldn't.
Here's the list my wife and I created.
| Category | Criteria | Reason |
Price | 450%-660% of combined pre-tax income | Based on keeping combined principal and interest payments under 30% of annual income. |
Location | Tokyo 23 Wards | Prefer East Tokyo (quieter and cleaner than the west, cheaper than the center). |
Construction Age | 5-15 years | After looking around, I didn't feel like living in places older than 15 years. Remodeled homes are fine, but after seeing a relative struggle with repairs after buying a 20+ year-old home, I applied this filter. Seismic design standards changed in 1981, so even older homes built after 1981 and remodeled are worth considering. |
Commute Time (door to door) | Within 40 minutes | I commute about 3 times a week, and my wife commutes about twice a week. |
Walking distance to the station | Within 10 minutes | Decided on under 10 minutes as it is convenient and reportedly good for retaining property value. |
Number of units in building | 40 or more units | I was told having at least 40 units prevents major issues even if some households default on fees. (Multiple real estate agents shared this opinion, so it seemed reasonable). |
Area | 55m2-73m2 | Based on the size with the highest turnover rate, appealing to a wide range of buyers like well-off singles, DINKs, and 3-person families. |
Why not a new build
The first agency we visited pushed new construction(just finished or to be completed in a year or two), and friends of ours had bought new, so we looked into it seriously. But holding every condition above constant except build year, new builds were simply too expensive. Going new would have meant compromising somewhere else on the list. We didn't particularly care about new for its own sake, so we picked candidates that met our conditions and bought one of those.
Why not a tower mansion
We visited a few early on and gave up.
There were hardly any tower mansions that satisfied all of our conditions in the locations we wanted.
And prices rise floor by floor, which apparently produces a class system inside a single building. That one spooked me.
This is hearsay, so take it for what it's worth. But I'd seen something similar play out in a mixed-use tower back in Korea, which made it hard to dismiss.
Timeline
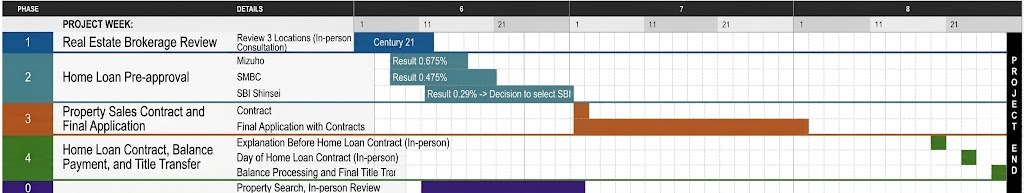
The purchase contract goes through on the basis of the pre-approval (事前審査). The full review (本審査) can only be applied for once you have those signed contract documents in hand.
Why we went with Century 21
Of the three agencies we consulted in person, they gave the most detailed explanations. The office atmosphere, the way we were handled, the whole thing felt professional. We decided without much deliberation.
That said, I'm told the variance between branches is large, so it's worth thinking about. Smaller agencies will cut the brokerage fee, but as a foreigner I worried about getting burned trying to save a little, so we went with a big firm.
Would I recommend Century 21 to someone else? Not necessarily. Fit with your specific agent matters, so I'd suggest visiting a few. And if you already know exactly what property you want, hunting down a place that discounts the brokerage fee is probably worth the legwork.
Comparing loan rates and terms
Based on reviews conducted in June 2024.
Me
- 3rd year at the company
- Small unlisted foreign company
- 5-year visa (Highly Skilled Professional)
My wife
- 2nd year at her company
- Unlisted mid-sized Japanese company
- Japanese national
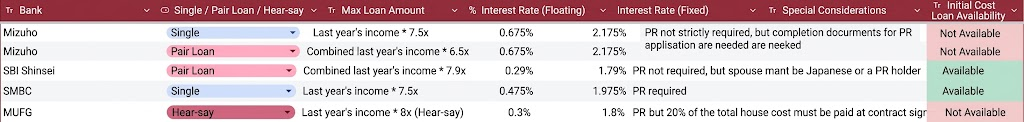
Fixed rates were variable +1.5% as a baseline.
Mizuho was the odd one out: permanent residency wasn't required, but they did want proof that I had applied for it. Thanks to that I now have a PR application filed, though their terms weren't good enough and we went with a different bank in the end.
Can you do this without permanent residency?
Yes. You can apply for a mortgage without PR, and as a single applicant too. See the notes in the table above.
Does the HSP visa get you preferential treatment?
I applied for pre-approval while on the Highly Skilled Professional visa, and got no preferential treatment at all. I asked the institution directly and they confirmed there is none. That said, banks differ. There may well be preferential terms at banks my wife and I didn't look into.
How much cash do you actually need?
Upfront costs came to 6.5% of the property price. Those costs can be financed too. But even if you finance everything, you still need the 手付金 (tetsukekin, the earnest money deposit) in cash at the contract stage, after pre-approval. I'm told 5–10% of the price is typical. Ours was 5%.
On the day the loan is disbursed, the portion you already paid as tetsukekin stays in your account. (It comes back to you.)
If the buyer or seller walks away after the contract is signed, that money is gone, and there can be additional damages on top. In our case, if the seller cancelled, we'd get double back. (So a cancellation would honestly have been a welcome outcome.)
So: even with a full loan, plan on having roughly 5% of the property price in cash.
What the loan review actually looks at
The applicant
1. Annual income
The benchmark is your withholding tax certificate (源泉徴収票) from the year before the review. My projected income for the year I applied was about 20% higher than the previous year, and I had documentation to prove it. I tried to make that case. It carried zero weight. Only the previous year's certificate counted.
2. Whether your employer is publicly listed
Mine isn't, and neither is my wife's. Counted against us.
3. The size of your employer
I work at the Japan office (about 30 people) of a foreign company with around 3,000 employees globally. For a mortgage review, nobody cares how many people you have overseas. They look at the domestic headcount. Counted against us.
4. Years of service
From the third year onward it apparently doesn't make much difference.
The property
The property is the collateral, so its condition affects the loan significantly. A good property makes approval comparatively easy. (If you can't pay, the bank has to repossess and auction it.)
Can you pass the pre-approval and then fail the full review?
I'm told that as long as you don't do something extreme between the two, like buying a car on credit, you'll pass 99% of the time.
Tools and sites we used
SUUMO — property listings.
Mansion Review — ratings and reviews of the buildings themselves. It breaks scores down across multiple dimensions, which made it useful input. Comparing against the data for where you currently live is a good way to calibrate.
Mansion Note — I used this mainly to check reviews and ratings of the nearest station itself.
Afterword
Eighteen properties met every condition on our list and made it to serious consideration. At the time of writing, about two months after we started looking, fourteen of those, including the one we bought, have sold. The number of listings is small to begin with, but turnover is quite fast.
Member discussion